


The banks made billions from Israelis’ checking accounts. Now they could have to pay it back
A court has certified a NIS 15 billion class action against four major banks over interest on checking balances, opening a legal challenge to one of the industry’s most profitable practices.
The court’s approval this week of a NIS 15 billion class action against four major banks, over their failure to pay interest on checking account balances, brings back into focus one of the biggest consumer distortions of recent years. The sharp increase in interest rates from 0.1% to 4.75% between April 2022 and May 2023 was a major event for the economy. In addition to fulfilling the Bank of Israel’s central mission of curbing inflation, the rate-hiking cycle exposed just how much banks could benefit from customers leaving large sums of money sitting in checking accounts.
The public was furious, the Knesset tried to advance legislation, the Bank of Israel called on banks to pass higher rates on to customers, and the Finance Ministry even imposed a special tax. Yet the impact on the banks’ bottom lines was limited. As interest rates rose, banks continued to hold hundreds of billions of shekels belonging to the public in checking accounts, using the funds to extend credit or placing them with the Bank of Israel, while paying customers an average of only about 0.1% on their balances. At an average rate spread of roughly 4.3 percentage points, that would amount to banks earning about NIS 430 for every NIS 10,000 held in a checking account, while paying customers just NIS 10.
Now, the class action certified this week against Leumi, Mizrahi-Tefahot, Discount and First International could fundamentally change that dynamic, and potentially succeed where other efforts have fallen short.
1 View gallery
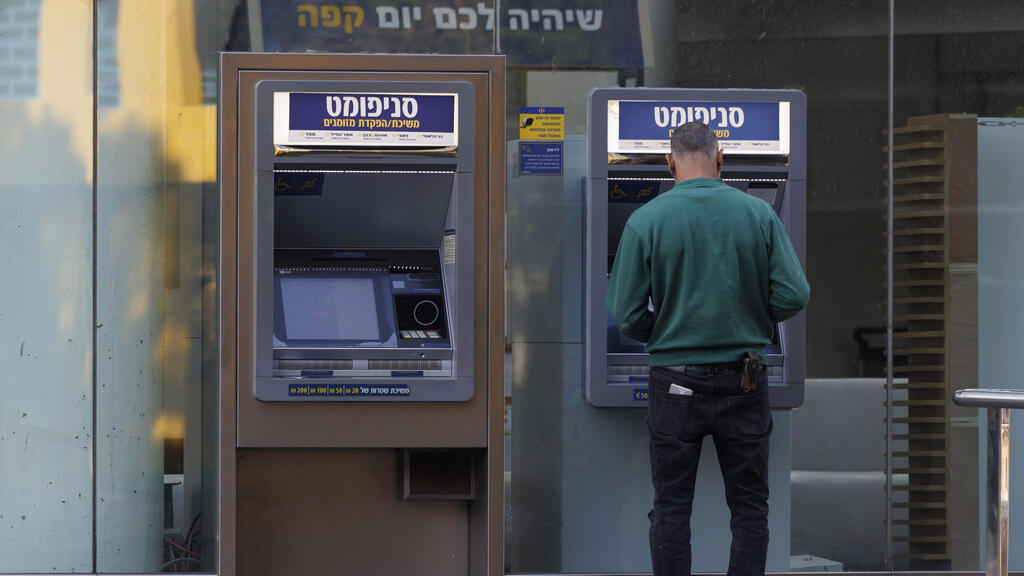
A First International Bank ATM. The ruling's impact will be limited without more competition in the sector.
(Photo: Kobi Wolf/Bloomberg)
Bank Leumi holds the largest share of checking account money among the four banks, at about 42%, meaning its theoretical exposure to the lawsuit is estimated at roughly NIS 6 billion. It is followed by Mizrahi-Tefahot at about 24%, Discount at about 19% and First International at about 15%. The exposure of Hapoalim, against which a separate lawsuit was filed, is on a similar scale to Leumi.
“Precedent-setting on the level of the Big Bang”
The Central-Lod District Court on Tuesday certified a class action against four of Israel’s five largest banks, Leumi, Mizrahi-Tefahot, Discount and First International, over claims that they should have paid customers interest on positive checking account balances. In his decision, Judge Shmuel Bornstein approved the suit on its central cause of action of “unjust enrichment,” while rejecting other causes of action, including misrepresentation and breach of the duty of good faith.
The approved class action covers the period from April 2022 to May 20, 2025, and seeks compensation for interest allegedly not paid on checking account balances. The potential damages have been estimated at more than NIS 15 billion, although the final amount, if any, remains to be determined.
The decision is unprecedented in its potential implications for the banks’ business model. It also comes after another blow to the sector earlier this year, when the Competition Authority declared the banks a concentration group in household services.
Until now, the banks’ main line of defense rested on account-opening agreements, which state that the payment of interest is at their discretion. However, the court ruled that the contracts do not tell the entire story. The fact that customers agreed to leave their money in checking accounts does not necessarily mean they gave banks permission to use those funds as a source of financing without compensation, according to the court’s reasoning.
“It’s precedent-setting on the level of the Big Bang,” Adv. Yitzhak Aviram, who represents the plaintiffs alongside Adv. Shahar Ben Meir, told Calcalist. “Never have courts intervened in the banks’ pricing. But for years the banks have been exploiting everyone. The court cut it short and to the point.”
Given the potential implications, the banks are expected to seek leave to appeal to the Supreme Court. The banks are also expected to rely, among other things, on the position of the Bank of Israel, which has opposed legal intervention in the pricing of checking accounts.
The decision carries enormous potential financial weight, assuming the courts ultimately determine that the banks were required to pay interest on checking account balances at rates comparable to those available on daily deposits. Even in a scenario in which the parties ultimately reach a settlement, the sums involved could run into billions of shekels, potentially dwarfing the roughly NIS 3 billion special tax imposed on the banks this year.
In parallel, a similar proceeding is being conducted against Bank Hapoalim on a separate track, with the case expected to reach the evidentiary stage in January. The Hapoalim case is more complex because the bank offers an automatic mechanism for moving funds from checking accounts into deposits, although the plaintiffs argue that the mechanism is not sufficiently accessible to the public. Hapoalim also offers a mechanism that offsets part of the interest charged on overdrafts based on checking account balances.
The compensation will flow to affluent customers
Despite the potential financial impact, the court’s decision is unlikely to appear immediately in the banks’ financial statements, and it is too early to assess its effect on their bottom lines. Under the Banking Supervision Department’s reporting directives, recognizing a provision requires two cumulative conditions: a high probability of loss and the ability to reasonably estimate its amount.
“As a rule, for the banks to make provisions there needs to be a probability of about 70% and up of a loss, and at this stage it was only approved to conduct the class action,” explains Lior Shilo, banking analyst at IBI Investment House. “In addition, you need to remember that the Bank of Israel provided the banks a pretty strong line of defense, when it stated that the banks should not be required to pay interest on checking account balances.”
The question of who stands to benefit from the lawsuit is more complicated. On one hand, most Israelis hold a positive balance in their accounts for at least part of the month, making the lawsuit relevant to a broad section of the population. The threshold set by the court for inclusion in the plaintiff class covers customers whose accounts had a positive balance of at least NIS 3,000 for one business day, or at least NIS 1,000 for three business days or more, between April 2022 and May 2025. The judge noted, however, that the definition of the class and the eligibility period could still be narrowed during the proceedings.
On the other hand, a large share of the public is unlikely to receive substantial compensation. Of about 5.6 million accounts, nearly half have up to NIS 5,000 in checking, with an average balance of only about NIS 1,200. Together, this group holds just 1.7% of Israel’s checking account balances. Some of these customers spend much of the month in overdraft or close to it, while a smaller portion may already be using daily deposits or moving excess cash into money market funds.
At the other end of the scale is the big money. About 37% of checking account balances, or roughly NIS 220 billion, sits in just 2.6% of accounts with balances of more than NIS 250,000. That means a substantial share of any compensation ultimately paid by the banks would flow to relatively affluent customers.
But that group is not necessarily made up entirely of sophisticated investors. Some may be elderly people with limited financial or digital literacy for whom the money sitting in a checking account represents their entire savings, and who were unable or unwilling to take advantage of the higher interest rates available elsewhere.
A boomerang effect on the consumer
In the long term, the legal proceeding, particularly if it ultimately results in a ruling against the banks, could bring significant changes to the market. The banks could be required to pay more reasonable interest on checking accounts in a high-rate environment, or at the very least to create and make accessible automatic mechanisms for transferring idle funds into interest-bearing products.
A legal determination that the existing model constitutes “unjust enrichment” would carry significance beyond the specific historical period covered by the lawsuit. Even if compensation were limited to the period in question, such a ruling could establish a new standard for the relationship between banks and their customers and create an incentive for banks to change their practices going forward. It could also give the Knesset additional impetus to pursue legislation affecting the banking sector.
But the proceeding could also have a significant side effect. This is where the Banking Supervision Department’s opposition comes in: It has warned against outside intervention in the banks’ pricing mechanisms.
The banks are unlikely to simply absorb a major loss of revenue. “If the suit is accepted and becomes a precedent,” Shilo says, “I assume the banks will price the relevant products accordingly for all customers, both on the checking side and on the credit side.”
In other words, Israeli consumers could experience a boomerang effect from another direction. Any substantial compensation paid for the past could eventually be reflected in higher interest rates on loans or indirectly through higher fees and service charges.
That is why, regardless of the outcome of the lawsuit, its impact on consumers will ultimately depend on the competitive environment in Israeli banking. A court ruling can change the rules governing what banks pay on checking balances, but without greater competition, the cost could potentially reappear elsewhere in the banking system.