


"When should you buy? When there is panic": Investors weigh Wall Street rout
Four senior investment managers offer different interpretations of the sharp selloff in technology and semiconductor stocks. Some see an opportunity to accumulate shares in profitable companies, while others warn that the market may still be underestimating the risks surrounding AI investment.
The sharp declines in Wall Street technology stocks, particularly in the semiconductor sector, are putting the investment strategies of Israeli institutional investors to the test. In recent years, these institutions have increased their exposure to companies benefiting from the artificial intelligence boom. The selloff intensified on Friday, November 20, when the Nasdaq plunged by 5.3%, bringing its weekly decline to approximately 10%. Semiconductor stocks were hit particularly hard, with the SOXX ETF, which tracks the sector, falling 10.55% in a single trading session.
Four senior investment managers in Israel's capital market, who spoke with Calcalist over the weekend, agree that the declines follow a prolonged period of exceptional gains and that investors have little reason to panic or flee the stock market. But they differ over whether the selloff presents an opportunity to buy shares and how seriously investors should view the risks to the technology sector's continued growth.
2 View gallery
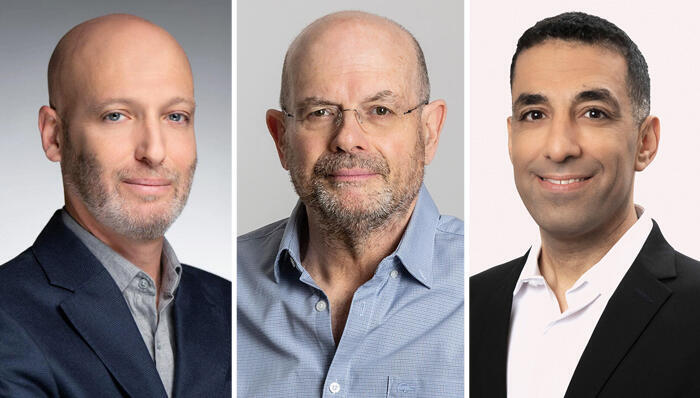
From right: Guy Mani, Yair Lapidot, Yotam Ironi
(Photos: Roi Mizrahi, Michal Visual, Rami Zaranger)
Yair Lapidot, founder and co-CEO of Yelin Lapidot, has warned in recent months that the extraordinary returns recorded by financial markets were unsustainable. Guy Mani, chief investment officer at Meitav Provident Funds and Pension, which oversees approximately NIS 250 billion in investments, says the institution has already begun using the decline to buy stocks. Eran Goldring, deputy CEO and head of the investment division at Analyst, sees potential opportunities in current price-to-earnings multiples. Yotam Ironi, head of international equities for the Provident and Pension division at Altshuler Shaham, meanwhile, points to a shift among investors toward safer assets.
Despite agreeing that markets have entered a period of correction, the four managers offer different explanations for what is driving the declines.
"What has happened in the markets over the past three years is anomalous," Lapidot said. "In Israel, we generated nearly a decade's worth of returns within just three years. The Israeli market surged by more than 100%, whereas, based on long-term historical averages, one might typically expect an annual return of 8% to 10%. Over the last three years, we have seen returns of nearly 30% annually, compounded. I have consistently argued that, under such circumstances, we are essentially 'selling the future.' This implies that, going forward, we will see lower returns."
Mani said the latest wave of selling had been building for about a month, driven by political developments in the United States, concerns over AI regulation and a more hawkish stance by the Federal Reserve.
"This triggered aggressive selling, initially in semiconductor stocks and subsequently across the broader indices," he said. "In recent days, we have witnessed massive sell-offs, which I believe are linked to the unwinding of leveraged positions and margin calls. In recent years, a significant portion of the American public has invested in the Nasdaq and the technology sector, and it is possible that some of these investments are leveraged."
Goldring also pointed to the role of leverage and automated trading in accelerating the selloff.
"There are margin calls, automated trading systems and leveraged funds that need to close out their exposure immediately," he said. "When a trade is 'crowded' and prices begin to fall, it creates a self-reinforcing cycle. In terms of intensity, this is reminiscent of the COVID-19 period and the era of tariffs."
Ironi said skepticism toward AI investments had been growing since early October, as investors began questioning the returns on the enormous sums being spent on infrastructure.
"It began with rising yields and financing difficulties, followed by questions about the return on the massive investments in server farms," he said. "Compounding this are concerns surrounding the sale of chips to China. Furthermore, last Friday marked the major monthly options expiration in the U.S. When such an expiration coincides with an already volatile day, it can act as a significant force multiplier."
Are the market declines an opportunity to buy stocks, or should investors reduce their exposure?
Lapidot cautioned against assuming that a period of excessive gains must inevitably be followed by a crash.
"Just because prices have risen too much, it doesn't mean they are bound to crash. It is possible that, instead of an average annual return of 8% to 10%, we might see 5% to 7% in the coming years. No one can time exactly when market corrections will begin or end," he said. "What has happened over the past three years was unhealthy, as investors began to view such returns as the norm, increasing their equity exposure precisely after the market had already rallied. In my view, the fact that some of the 'air' is now coming out of the markets is an excellent thing."
Mani said Meitav had begun buying shares gradually during the downturn, rather than attempting to predict when the market would reach its bottom.
"We are acting gradually. During sharp declines, like the one we saw on Friday, we tend to move slightly against the trend and begin taking small positions in stocks. As the downturn persists and valuation multiples contract, these stocks become increasingly attractive," he said. "We are still talking about companies that are growing and generating significant profits. While the declines might continue due to the immense pressure stemming from leverage and the unwinding of positions, I believe that those who gradually accumulate shares in high-quality companies will ultimately benefit."
Goldring also sees opportunities in the selloff, although he cautioned against making sweeping changes to investment portfolios.
"When should you buy? When there is panic," he said. "You might shift a portion of your investments from other sectors into technology, though, of course, this must be done with careful risk management. You could also be wrong, in which case you'll take a hit. That is why we operate only at the margins; we don't make dramatic changes to the portfolio."
Lapidot said investors should distinguish between companies whose share prices have fallen because of excessive previous gains and those whose businesses have genuinely deteriorated.
"We must also remember what happened in 2008 and March 2020. We haven't reached that point yet. Some stocks have fallen by tens of percent, though some had previously risen by enormous margins," he said. "On the other hand, when prices drop, it is certainly a time to consider shifting toward stocks that have been hit extremely hard, even in cases where such a decline wasn't necessarily justified."
Analyst is among the institutional investors with significant exposure to the semiconductor sector. Data as of the end of June 2026 show that the investment firm held approximately NIS 1.1 billion in the SOXX ETF, which tracks semiconductor stocks. This was the largest holding in the fund among the institutional investors examined, compared with approximately NIS 868 million held by Harel Provident and Pension and NIS 304 million by Mor Provident and Pension. Analyst managed approximately NIS 91.1 billion in provident fund assets at the end of June, meaning its SOXX holding alone represented around 1.2% of those assets, before accounting for any additional exposure to semiconductor companies.
The question is whether the selloff reflects a temporary reassessment of valuations or a deeper shift in expectations for corporate profits.
Goldring said the most striking development was the contraction in valuation multiples, even as analysts' earnings forecasts remained relatively stable.
"What is interesting is the unusual contraction in valuation multiples. Essentially, the market is signaling that it does not believe the analysts' earnings forecasts," he said. "There are two possibilities: either the analysts are correct and the market is wrong, in which case things will eventually correct themselves, or we will begin to see downward revisions to earnings forecasts. In the meantime, looking at data from FactSet, the forecasts have not changed significantly."
Goldring cited the technology sector's forward price-to-earnings multiple as evidence of how much valuations have contracted. According to FactSet's November 20 report, the S&P 500 Information Technology sector was trading at 16.3 times forward earnings, compared with a five-year average of 25.4 and a 10-year average of 23.1.
The figures point to a striking disconnect between share prices and earnings expectations. Since September 30, forward earnings estimates for the Information Technology sector have risen by approximately 9.2%, while its share prices have fallen by around 16%. In other words, analysts have continued to raise their profit forecasts even as investors have sharply reduced the prices they are willing to pay for those earnings.
Lapidot said the AI boom was fundamentally different from the dot-com bubble, but warned that the enormous investment required to build AI infrastructure could eventually become a source of vulnerability.
"AI is a completely real phenomenon, unlike the dot-com bubble of 2000. This time, we are dealing with massive corporations generating enormous sales and profits. Nvidia is the most extreme example," he said. "However, investments in building server farms, covering processors, memory, electricity and cooling, are reaching the trillions of dollars. If the companies investing hundreds of billions discover that their return on investment falls short of expectations, they will likely slow their pace of expansion. Once the rate of investment drops, Nvidia could see its sales decline by tens of percent. This may not be happening immediately, but it could certainly occur within the next year or two."
Mani was more optimistic about the financial resilience of the major technology companies investing in AI infrastructure.
"The giant companies building AI infrastructure are investing massive sums. However, a slight reduction in their capital expenditures would be enough for them to return to generating very strong cash flows," he said. "These are companies that continue to grow and remain profitable. Looking at the long term, the companies leading the world are still the technology companies."
Ironi said the AI industry was approaching a critical stage in which investors would increasingly demand evidence that the technology could support sustainable business models.
"The AI sector is currently at a stage where its business model needs to prove itself. It is clear that there is significant technology here, along with an emerging business model, but the market is still trying to determine which companies will emerge as the major winners," he said. "This is similar to the era of the internet, when business models eventually took shape and certain companies became the big winners."
How should investors act now, and what will signal that the market turmoil is over?
Lapidot said investors should resist the temptation to make dramatic changes in response to short-term market movements and maintain an equity allocation suited to their individual risk tolerance.
"I don't think one should flee the market. Every investor should maintain an equity allocation that suits them, rather than increasing it out of euphoria following a 100% gain over three years," he said. "I have always warned against using leverage on stocks or investing in leveraged instruments. These are 'suicidal' instruments, pure gambling. There is no need to flee the market the moment you see a decline."
Ironi said the current market behavior reflected a classic shift toward safer assets, commonly known as "risk-off."
"This time, we are seeing classic behavior: a shift toward safer assets, known as 'risk-off.' When stocks fall sharply, government bonds tend to rise. This indicates that investors are seeking a 'safe haven' and generally prefer to reduce risk. Therefore, it is worth considering a more diversified portfolio in terms of stock and bond holdings."
As for when the turbulence might end, Ironi said investors should look for signs that the indiscriminate selling is giving way to more selective trading.
"I'm always looking at the screens for the first signs of stabilization. One significant indicator is when we begin to see divergence among stocks, even within sectors at the heart of the storm. Some companies rise while others fall," he said. "This suggests that the market is no longer selling everything off indiscriminately out of hysteria, but is instead beginning to distinguish between individual companies. When the screen starts to show a mix of movements, it usually indicates that investors are beginning to think more clearly again."