


“If you want to stand out as a GP, it's not enough to deploy capital and bring good performance.”
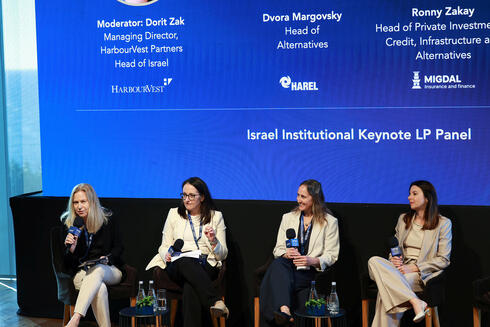
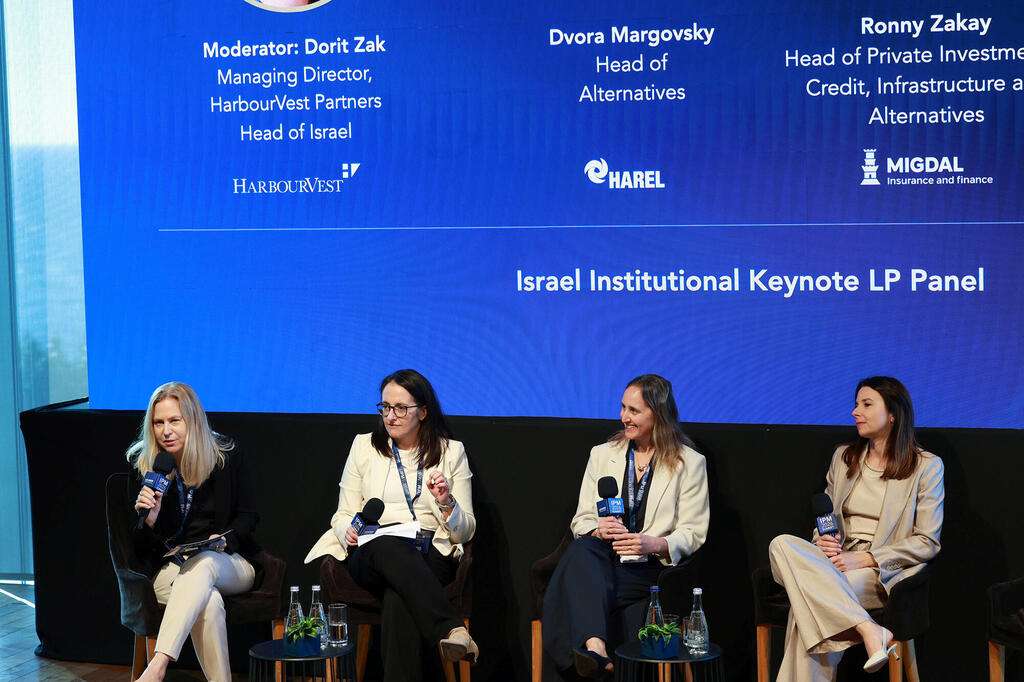
Ronny Zakay, Head of Private Markets, Migdal Insurance, was speaking as part of the Israel Institutional Keynote LP panel which concluded Leader Private Capital’s Israel Private Markets Summit (IPM) on Tuesday at the The Peres Center for Peace and Innovation in Tel Aviv.
“If you want to stand out as a GP, it's just not enough to deploy capital and bring good performance,” said Ronny Zakay, Head of Private Markets, Migdal Insurance, during an all-female panel which concluded Leader Private Capital’s Israel Private Markets Summit (IPM) on Tuesday at the The Peres Center for Peace and Innovation in Tel Aviv.
The Israel Institutional Keynote LP panel, which was moderated by Dorit Zak, Managing Director, Head of Israel at HarbourVest Partners, included Dvora Margovsky, Head of Alternatives, Harel Insurance & Finance, Ronny Zakay, Head of Private Markets, Migdal Insurance, and Lena Krupalnik, Head of the Citizens of Israel Fund, Bank of Israel.
Distributions have been slow for a very long time. How does this change your plans for 2027 when you think about asset allocations?
Ronny Zakay: “Generally, we're a long-term investor and we prioritize long-term performance and long-term value creation rather than short-term cash flow. So we are patient on that matter regarding DPI. Having said that, it is more difficult to allocate additional capital to a manager who hasn't returned enough distributions from older funds. And I think that dynamic is well known in the market and that's the reason that we're seeing so many continuation vehicles.”
So theoretically, if you had to cut 20% of GP relationships, nobody likes that, but it happens. What would determine who stays and who goes?
Zakay: “The basic criteria that we use when we decide to invest in a manager is still there. And we monitor this, of course, during the investment period and the harvest period. Sustainable performance, stable teams, which is super important, value creation, alignment of interest.These are the basics and they're still there.
“If we have a manager that's constantly underperforming or teams that we feel are falling apart, those, of course, would be the first GPs that we would cut off.
“Looking at Israeli, and not only Israeli, all institutional investors, I think over the past decade they've become a lot more sophisticated and a lot more involved in their alternative investments. And I think that if you want to stand out as a GP, it's just not enough to deploy capital and bring good performance.”
Where do you think the future lies for specialists or generalists?
Dvora Margovsky: “The answer depends on which sector you look at. You will tend to find specialists in markets or sectors where there's a lot of opportunities and you really can enjoy a lot of deal flow and be a specialist.
“You will see more generalists in the media market where you need to have more across sector data and relationships and I think those are also funds that can bring relative value because they understand how one sector is performing over the other, which is also very important for an institutional investor because we always compare the different alternatives.”
Lena, what do you think?
Lena Krupalnik: “I think specialization is an advantage but that's also a constraint. For a specialist, obviously the specialist has a deeper knowledge of the sector, better connections, better sourcing but the question that we ask is what happens if the specific sector is not attractive enough, if it is expensive? Can the manager slow the deployment pace? Can they raise smaller funds? Can they return capital to investors?
“We don't have a structural preference of one over the other. We do look for managers that can be selective and can adjust when the market opportunity is changing or becoming not attractive enough.”
What private market strategy do you think is most likely to look more meaningfully larger in institutional portfolio than it is today? Krupalnik: “I think two strategies will be larger than they used to be.
“One is private credit and the other is secondaries. I think private credit approval itself presented very strong results even though the interest rates went up and we were all worried about the ratio of the covenant and the quality of the underwriting and we see returns and we see the outperformance of this sector over private equity and also the liquid debt. So this strategy I think was a bit of a niche strategy, let's say five years ago and I think it will be a larger portion of institutional investors going forward.
“The other strategy I think will be secondaries. It's a very important tool for LPs and GPs to continue their growth managing their liquidity and I think we saw the secondaries as something to do with LPs that were in a very tight position of cash flows using and going forward I think it will be just liquidity going to the market and for institutional investors switching strategies and managing their portfolios.”