



Analysis
Israel's 1.5% inflation rate may be more mirage than reality
The headline figure masks a faster underlying trend, rising rents and a weak end to 2025 that will soon fall out of the annual calculation.
The Consumer Price Index (CPI) rose by 0.7% in August, in line with market expectations. As a result, inflation over the past 12 months stands at 1.5%, its lowest level since 2021 and roughly unchanged from the previous month, despite expectations for a slight increase to 1.6%.
That headline figure can be misleading, however, because the same release contained three other figures that are almost as important. Taken together, the four figures tell very different stories.
The second figure, 0.3%, is the seasonally adjusted increase in the index. This suggests that more than half of August's rise was attributable to seasonal factors rather than underlying price pressures. The third figure is 2%, the annualized rate of increase based on the Central Bureau of Statistics' trend data for May through August. The fourth is 0.7%, representing the increase in the index excluding housing costs over the past year.
1 View gallery
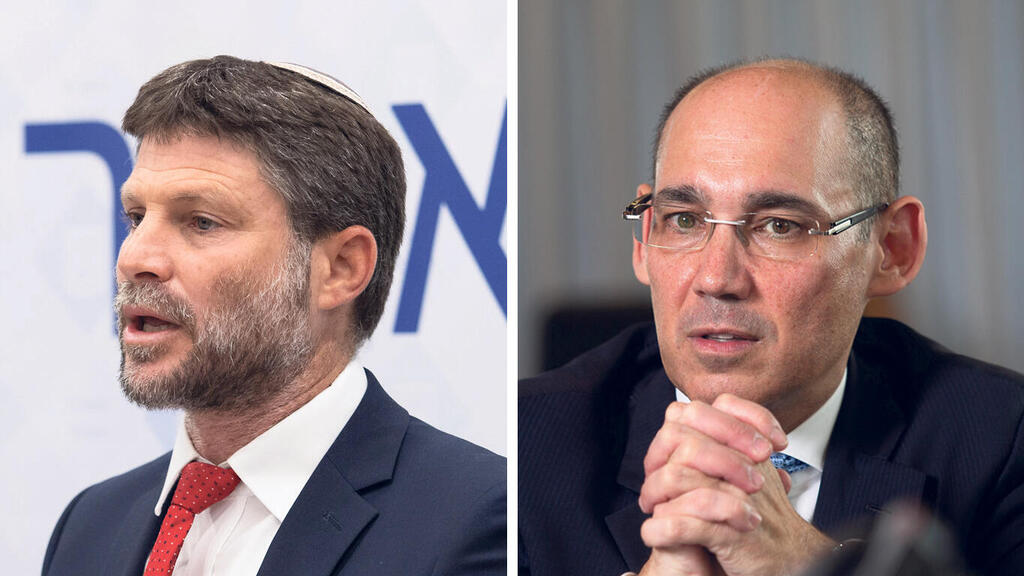
BOI Governor Amir Yaron (right) and Finance Minister Bezalel Smotrich
(Alex Kolomoisky)
These four figures point to four different interpretations of the inflation picture. Anyone looking only at the 1.5% annual rate is missing a more complicated story.
The monthly breakdown helps explain why. Prices for overseas travel and flights rose by 9%, contributing 0.41 percentage points to the overall index, nearly two-thirds, or 60%, of the total increase. Hotel and guesthouse prices rose by 12%, vehicle rental prices by 25.5%, and fuel prices by 7.2%, with fuel contributing another 0.18 percentage points.
Travel and fuel therefore account for almost the entire monthly increase, while other components largely offset one another. The biggest offset came from car insurance, whose price fell by 8%, reducing the index by 0.15 percentage points, the largest negative contribution in the report. The CBS does not provide an explanation for the decline. Without it, the CPI would have risen by approximately 0.85% rather than 0.7%.
The more important issue, however, is the 1.5% annual figure. At first glance, it looks encouraging: it is comfortably within the Bank of Israel's 1%-3% annual inflation target and close to its midpoint. But that figure is being held down by an unusually weak period at the end of 2025.
Since the beginning of this year, the CPI has already risen by 2.1% in just eight months, putting inflation above the midpoint of the target range. The discrepancy between the 1.5% annual rate and the 2.1% increase since January is largely explained by September through December 2025, when the index fell by a cumulative 0.6%.
Those months will drop out of the 12-month calculation one by one over the next four CPI releases. Even if prices remain completely flat in the coming months, the annual inflation rate will move toward 2%. That is not a forecast; it is simply arithmetic. In that sense, the current 1.5% figure may be less representative of the inflation environment than it appears.
The fourth figure, 0.7% inflation excluding housing, helps identify what is actually driving Israeli inflation. Without housing, prices rose by only 0.7% over the past year, roughly half the headline rate.
Food prices, which routinely generate attention when they rise, fell by 0.5% in August. The decline was broad-based, extending across dozens of product categories, while clothing and furniture prices also fell. In Israel in 2026, there is little evidence of broad-based inflation in goods, with fuel prices a notable exception amid the war with Iran. The more persistent pressure is in services, and, within services, particularly housing.
Hidden within the housing component is a figure that could determine the direction of inflation in the months ahead. Rents paid by tenants renewing their leases rose by 2.6%, while rents for new tenants rose by 4.4%.
The gap between those figures matters because it acts as a conduit through which higher market rents gradually feed into the measured CPI. As existing leases expire and tenants sign new ones, the official rent index moves toward the higher prices being paid by new tenants.
This is also a form of price pressure that monetary policy can address only imperfectly. The underlying constraint is on the supply side: there is not enough housing relative to demand. Interest rates can influence demand, but they cannot directly create additional housing supply. More broadly, monetary policy tends to have less immediate influence over service prices than over goods whose demand is more sensitive to the cost of credit.
This is where politics enters the picture.
On September 1, the Bank of Israel lowered its benchmark interest rate to 3.25%, its fifth cut in less than a year. The next decision is scheduled for October 21, just six days before the election for the 26th Knesset. On the same day, the Bank's Research Department is due to publish its forecast, while Governor Amir Yaron is expected to deliver a speech presenting a detailed economic assessment. Six days earlier, on October 15, the September CPI will be published.
Political pressure on the Monetary Committee is nothing new. Finance Minister Bezalel Smotrich described the July rate cut as "a negligible reduction that fails to address the economy's challenges." But the timing of the October decision makes the political optics unusually sensitive. With the election less than a week away, a rate cut could be portrayed as a response to calls for cheaper credit, while a decision to hold rates steady could be criticized as a failure to act.
This is precisely the kind of situation in which a central bank would prefer to minimize political perceptions surrounding its decisions, even if doing so means tolerating a short-term delay in further rate cuts.
A Monetary Committee that cuts rates six days before an election could face accusations that it is intervening in the political environment. A committee that leaves rates unchanged would be accused by others of failing to respond to economic pressures. There is no decision that eliminates the political interpretation.
But holding rates steady would at least be straightforward to defend on economic grounds. If the trend rate of inflation is 2.0%, business-sector wages are rising by 6.4%, unemployment has fallen to 2.8%, indicating a very tight labor market, and Governor Yaron has already said inflation is expected to return to around 2% in the coming months, the committee would not need an elaborate explanation.
Anyone reading references on October 21 to "uncertainty" and "convergence toward the midpoint of the target range" could reasonably interpret them as signaling a pause in the rate-cutting cycle.
The next government, whatever form it takes, may therefore inherit an economy in which inflation is once again approaching the middle of the target range, while much of the remaining price pressure is concentrated in housing. And that is a problem the central bank's interest-rate tool can influence only indirectly: the deeper constraint lies in housing supply.